TA14 AUTHORITY GOVERNANCE INSTITUTION · INDEPENDENT CONCEPT SHOWROOM
Public Expenditure Admissibility Architecture
Public money is a consequence. Explore the proposed TA14 decision boundary between an invoice, a lawful release and a verifiable public outcome.
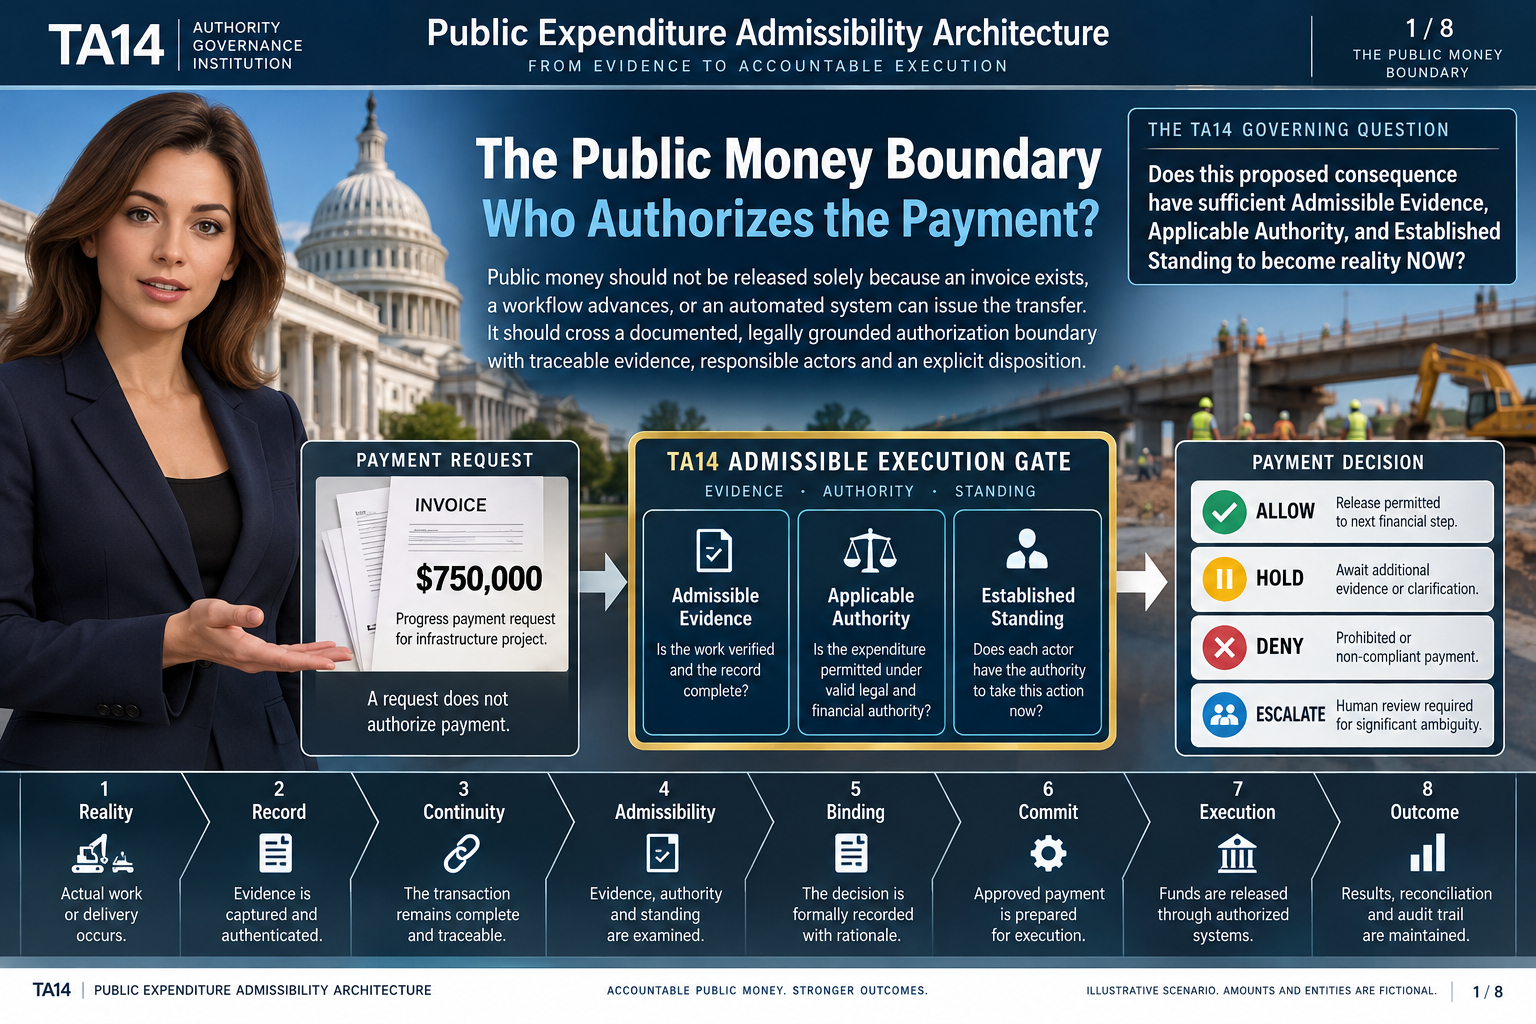
Does this proposed consequence have sufficient Admissible Evidence, Applicable Authority, and Established Standing to become reality NOW?
Educational concept only. All amounts, people, documents and illustrated outcomes are fictional. No government deployment, certification, legal opinion, fraud reduction or validated savings are claimed. Existing agency controls and lawful payment authorities remain in control.
Download technical reference (PDF) ↗
1 / 8 · The Public Money Boundary
Samantha's lesson transcript
A proposed seven hundred and fifty thousand dollar construction payment is a real-world consequence, not merely a document moving through software. The invoice tells us what a contractor requests. It does not itself establish completion, entitlement, lawful funding, or who can approve release. TA14 asks the governing question: does this proposed consequence have sufficient Admissible Evidence, Applicable Authority, and Established Standing to become reality NOW? Existing public financial controls remain legally controlling. This concept places a reviewable decision boundary beside them and preserves the exact transaction, reviewer, sources and rationale. Our example is fictional and demonstrates a proposed approach, not a deployed government system.
INTERACTIVE EXAMINATION · FICTIONAL DATA
Can the $750,000 draw proceed?
Set the conditions and run a simulated TA14 gate. This is an educational model, not a legal decision, payment authorization or connected financial system.
From decision to real-world outcome
Reality → Record → Continuity → Admissibility → Binding → Commit → Execution → Outcome.
This conceptual examination does not replace statutory appropriations, agency approvals, treasury controls, procurement requirements or independent auditing. Agencies must validate applicability, operational burden and incremental value before any production use.
Browse other TA14 showrooms →